4 DIY Solutions for Your Bathroom Space
Martin Jensen • February 15, 2018

All of us are looking for ways to make our living spaces more efficient whilst keeping the style intact; and certainly the bathroom space is no exception. The question becomes, “How do I do this without spending a small fortune on renovations and upgrades?” The answer is simple...You get creative!

The following are four stylish bathroom hacks that will help you declutter and organize, all for the cost of a few cups of coffee (or tea, if that’s your thing!)

Creative Shelving Units

The first (and most obvious) solution for getting your bathroom clutter organized is by way of conveniently placed, ideally designed, and most definitely inexpensive shelving units. This may sound daunting, especially if you, like me, lack meaningful shelves in any and all of your bathroom spaces. But never fear! There are easy and effective ways to make this happen!

Wicker baskets (and the like)
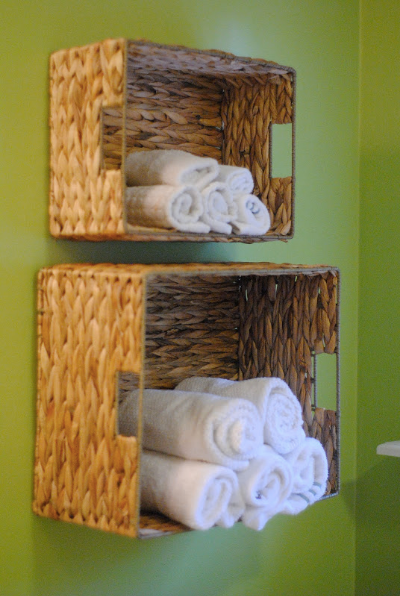
This image is from diyready.comand can be found here

Baskets (of various sizes) can be hung from any wall in your bathroom via a drywall anchor (or two) and a simple screw (or two). This technique will not only showcases a classic, rustic homestead piece (the basket); it will also give you ample room to store whatever it is that you need to store.

Obviously, if you don’t have baskets, other items can be utilized here. The key is the shape. If it’s deep enough to hold that which you need it to hold, and “the look” is there, than go for it!

The Hanging Shelf

Nothing beats the satisfaction of framing your own shelf. Now, before you get scared and run...relax. This job includes only a few tiny pieces of lumber, a small length of rope, a small can of wood stain, and a hanger (with another drywall anchor/screw combo). This piece can be easily hung over a toilet or on an empty wall. Plus, not only does it provide shelf options, you can beam with pride when you tell your guests that you fashioned it yourself, out of a tree that you found in the forest, and cut down, yourself...right? Too far?

Custom Towel Rack Solutions

Related to the shelving units, we find ideas related to hanging towels. Simply, you’d be mistaken if you stopped at the classic rack; because there’s a world of options out there for you to try out.

The Ladder Rack

An old wooden ladder, properly restored, can act as a great hanging rack for towels, face cloths and clothing items fresh out of the washer.
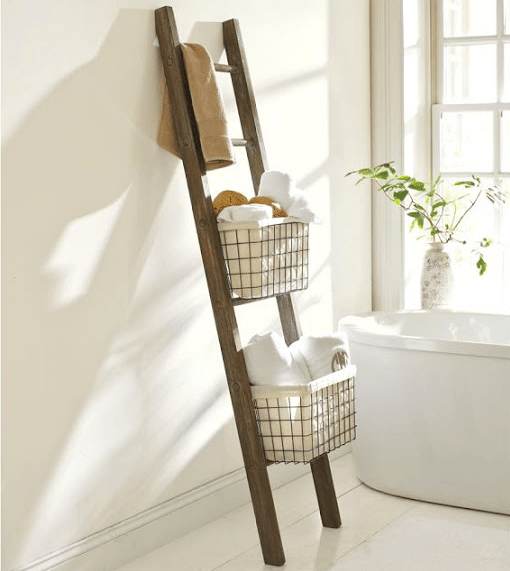
This image is from charmbraceletdiva.blogspot.ca and can be found here

“His” and “Hers”

His and her towel racks are not only interesting design wise; they’re functional. No longer will your spouse have rights to your towel because he or she didn’t know that it was yours. Those days are over.

Wine Rack/Towel Rack
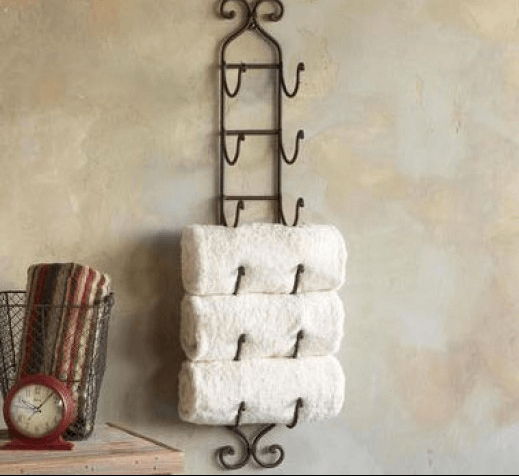
This image is from hubpages.comand can be found here

Yes! The wine rack has uses for things other than wine. namely...towels! In all seriousness though, these racks can be very inexpensive and can hold several towels at a time; all the while looking classy, interesting and unique to boot! What’s not to like?

Vanity Organization

Most bathrooms that I’ve seen (and experienced) contain drawers that are simply overflowing with stuff. Avoid this travesty at all costs by dividing (and therefore conquering) the drawer’s contents. Kitchen utensil holders work fabulously here. These pieces are simple, functional, and nobody has to see them but you, so the questions surrounding kitchen organizational tools in your bathroom will be minimal.

Continue with your vanity realignment by adding some simple hanging shelves into the inside the cabinet door. A simple magazine rack can work well here, and can be attached via a couple small screws (just make sure you don’t go so far as to pierce the outer side of the door).

The Mason Jar (For all your hipster storage needs)
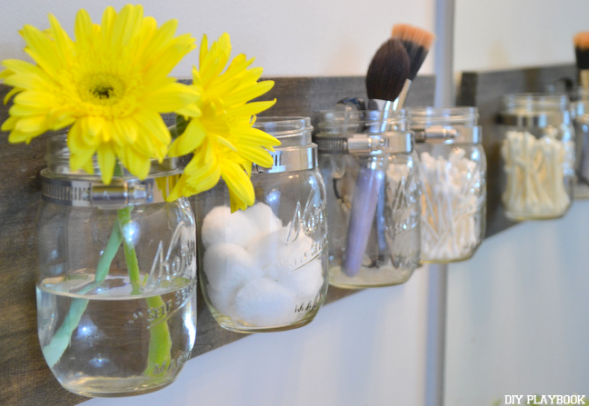
This image is from thediyplaybook.comand can be found here

Mason jars are useful for lots of things: storing jams, holding pickled items and also dispensing soap...That’s right! Also (and perhaps a little more seriously), these jars can be formed into wonderful mini storage units. They look great, too!

There are obviously lots more ideas out there, but hopefully these few have gotten your creative juices flowing, and have ignited your imagination. There’s lots you can do; so what are you waiting for?
RECENT POSTS
By Martin Jensen September 16, 2026
Why the Property Matters When You’re Qualifying for a Mortgage When qualifying for a mortgage, lenders typically look at four core areas: Income Credit Down payment or equity The property itself Most buyers focus heavily on income, credit, and savings—and for good reason. But even if those boxes are checked, the property can still determine whether a mortgage is approved. Why Lenders Care About the Property From a lender’s perspective, the property is the collateral for the mortgage. In the unlikely event of default, they need to know the home can be sold quickly and at fair market value to recover their funds. Because of this, lenders are careful about the condition, value, and marketability of any property they finance. Homes that are in poor repair, unconventional, or overpriced can raise red flags—even when the borrower is well qualified. Appraisals Are Always Part of the Process Every mortgage requires an appraisal to confirm value. Insured mortgages (through CMHC, Sagen, or Canada Guaranty) often use an automated valuation model completed online. Conventional mortgages typically require a full, on-site appraisal by a certified appraiser. This appraisal is not optional and happens after an offer is accepted—not at the pre-approval stage. Why Pre-Approvals Aren’t a Guarantee A pre-approval is a great first step, but it only assesses you, not the property. Once you’ve made an offer, the lender must approve the specific home you’re buying. Understanding this upfront helps avoid surprises and confusion later in the process. The Risk of Buying Without a Financing Condition In competitive markets, buyers sometimes remove financing conditions to strengthen their offer. However, this comes with risk. If the appraisal comes back low—or the lender is concerned about the property’s condition—you could be denied financing after the offer is firm. In that scenario, your deposit may be at risk. Buying a Home That Needs Work If you’re considering a property that isn’t in perfect condition, there are solutions. A purchase plus improvements program allows you to buy a home and include renovation costs in your mortgage. The process is structured and requires planning, but it can be an excellent way to turn a fixer-upper into a great long-term investment. Final Thoughts Mortgage approval isn’t based solely on your finances—the property matters just as much. Knowing this ahead of time helps you make smarter offers, reduce risk, and plan more effectively. If you’re buying a property that needs work or want clarity on how a lender may view a specific home, feel free to reach out. I’d be happy to walk you through your options and help you plan with confidence.
By Martin Jensen September 9, 2026
So, you’re thinking about buying a home. You’ve got Pinterest boards full of kitchen inspo, you’re casually scrolling listings at midnight, and your friends are talking about interest rates like they’re the weather. But before you dive headfirst into house hunting— wait . Let’s talk about what “ready” really means when it comes to one of the biggest purchases of your life. Because being ready to own a home is about way more than just having a down payment (although that’s part of it). Here are the real signs you're ready—or not quite yet—to take the plunge into homeownership: 1. You're Financially Stable (and Not Just on Payday) Homeownership isn’t a one-time cost. Sure, there’s the down payment, but don’t forget about: Closing costs Property taxes Maintenance & repairs Insurance Monthly mortgage payments If your budget is stretched thin every month or you don’t have an emergency fund, pressing pause might be smart. Owning a home can be more expensive than renting in the short term—and those unexpected costs will show up. 2. You’ve Got a Steady Income and Job Security Lenders like to see consistency. That doesn’t mean you need to be at the same job forever—but a reliable, documented income (ideally for at least 2 years) goes a long way in qualifying for a mortgage. Thinking of switching jobs or going self-employed? That might affect your eligibility, so timing is everything. 3. You Know Your Credit Score—and You’ve Worked On It Your credit score tells lenders how risky (or trustworthy) you are. A higher score opens more doors (literally), while a lower score may mean higher rates—or a declined application. Pro tip: Pull your credit report before applying. Fix errors, pay down balances, and avoid taking on new debt if you’re planning to buy soon. 4. You’re Ready to Stay Put (At Least for a Bit) Buying a home isn’t just a financial decision—it’s a lifestyle one. If you’re still figuring out your long-term plans, buying might not make sense just yet. Generally, staying in your home for at least 3–5 years helps balance the upfront costs and gives your investment time to grow. If you’re more of a “see where life takes me” person right now, that’s totally fine—renting can offer the flexibility you need. 5. You’re Not Just Buying Because Everyone Else Is This one’s big. You’re not behind. You’re not failing. And buying a home just because it seems like the “adult” thing to do is a fast way to end up with buyer’s remorse. Are you buying because it fits your goals? Because you’re ready to settle, invest in your future, and take care of a space that’s all yours? If the answer is yes—you’re in the right headspace. So… Are You Ready? If you’re nodding along to most of these, amazing! You might be more ready than you think. If you’re realizing there are a few things to get in order, that’s okay too. It’s way better to prepare well than to rush into something you're not ready for. Wherever you’re at, I’d love to help you take the next step—whether that’s getting pre-approved, making a plan, or just asking questions without pressure. Let’s make sure your homebuying journey starts strong. Connect anytime—I’m here when you’re ready.
By Martin Jensen September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.