Using Your Home Equity to Stay Just a Little Bit Longer
Martin Jensen • April 4, 2018

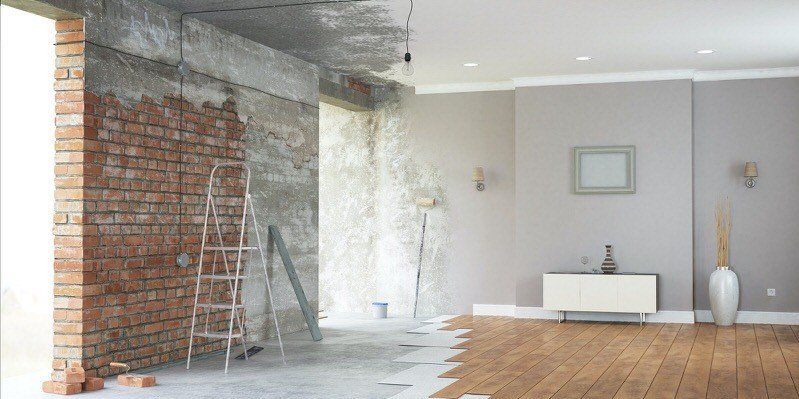
Last month, the article "Can't find the Perfect Property in Your Price Range" was published on the blog, where the purchase plus improvements program was outlined as a way to buy and renovate a property at the same time. If you are looking to buy a new home, but can't find something you love, this article is certainly worth a read! But what if you don't want to move? What if you like the place you're in, but it could use a few upgrades? Well, here are some ways you might be able to stay, just a little bit longer!

Introducing the mortgage refinance, and the refinance plus improvements. Both products allow you to leverage your home equity for home improvements.

Refinance

If your mortgage balance is less than 80% of your property's value, then assuming you qualify (given the latest changes to mortgage qualification), you can access the equity built up in your home to that 80% level. Lenders will typically ask what the funds are going to be used for, however you won't have to prove anything after the fact. You should be able to access up to $200,000. Assuming you have the equity, a refinance is a really great way to access funds for various reasons, here are just a few:

  • Renovate your house
  • Consolidate your high-interest debts
  • Help your children pay for education
  • Top up your investments
  • Access money for a downpayment on a vacation property
  • Start a new business (just don't quit your day job)
    … Or any combination of the above

But what happens if you want to do some renovations to your property, but your mortgage balance is more than 80% of your home's value? That's where the refinance-plus-improvements comes in.

Refinance-Plus-Improvements

Although guidelines will vary from lender to lender, the refinance-plus-improvements will allow you to access up to 80% of your property's existing value, plus the cost of the renovations. Most lenders will consider 10% of the initial value of the home, or $40,000, whichever is less, to be included for renovations. So when you take the existing value of your home and add the suggested cost of the renovations, this becomes the improved value. The mortgage is then based on the improved value, instead of your existing value.

However, the catch here is that the renovations have to increase the value of your home accordingly. And the lender wants to ensure that the renovations have been completed, and the value of the property has been increased before they will actually let you have access to the money. So, although the cost of the renovations can be added to the mortgage, it's your responsibility to pay for the renovations up front, and once the improved value is substantiated by an appraisal, then the funds will be released from the lawyer's trust account.

Securing a purchase-plus-improvements is certainly a little more tricky than executing on a refinance, but if you don't have enough equity saved up, this might just be the product that allows you to access your home equity in order to increase the value of your home, and give you a nicer home to live in. Win win.

If you have any questions about either a refinance or a refinance plus improvements, and what each of these would look like given your financial situation, please don't hesitate to contact me anytime, I'd love to work with you!
RECENT POSTS
By Martin Jensen September 16, 2026
Why the Property Matters When You’re Qualifying for a Mortgage When qualifying for a mortgage, lenders typically look at four core areas: Income Credit Down payment or equity The property itself Most buyers focus heavily on income, credit, and savings—and for good reason. But even if those boxes are checked, the property can still determine whether a mortgage is approved. Why Lenders Care About the Property From a lender’s perspective, the property is the collateral for the mortgage. In the unlikely event of default, they need to know the home can be sold quickly and at fair market value to recover their funds. Because of this, lenders are careful about the condition, value, and marketability of any property they finance. Homes that are in poor repair, unconventional, or overpriced can raise red flags—even when the borrower is well qualified. Appraisals Are Always Part of the Process Every mortgage requires an appraisal to confirm value. Insured mortgages (through CMHC, Sagen, or Canada Guaranty) often use an automated valuation model completed online. Conventional mortgages typically require a full, on-site appraisal by a certified appraiser. This appraisal is not optional and happens after an offer is accepted—not at the pre-approval stage. Why Pre-Approvals Aren’t a Guarantee A pre-approval is a great first step, but it only assesses you, not the property. Once you’ve made an offer, the lender must approve the specific home you’re buying. Understanding this upfront helps avoid surprises and confusion later in the process. The Risk of Buying Without a Financing Condition In competitive markets, buyers sometimes remove financing conditions to strengthen their offer. However, this comes with risk. If the appraisal comes back low—or the lender is concerned about the property’s condition—you could be denied financing after the offer is firm. In that scenario, your deposit may be at risk. Buying a Home That Needs Work If you’re considering a property that isn’t in perfect condition, there are solutions. A purchase plus improvements program allows you to buy a home and include renovation costs in your mortgage. The process is structured and requires planning, but it can be an excellent way to turn a fixer-upper into a great long-term investment. Final Thoughts Mortgage approval isn’t based solely on your finances—the property matters just as much. Knowing this ahead of time helps you make smarter offers, reduce risk, and plan more effectively. If you’re buying a property that needs work or want clarity on how a lender may view a specific home, feel free to reach out. I’d be happy to walk you through your options and help you plan with confidence.
By Martin Jensen September 9, 2026
So, you’re thinking about buying a home. You’ve got Pinterest boards full of kitchen inspo, you’re casually scrolling listings at midnight, and your friends are talking about interest rates like they’re the weather. But before you dive headfirst into house hunting— wait . Let’s talk about what “ready” really means when it comes to one of the biggest purchases of your life. Because being ready to own a home is about way more than just having a down payment (although that’s part of it). Here are the real signs you're ready—or not quite yet—to take the plunge into homeownership: 1. You're Financially Stable (and Not Just on Payday) Homeownership isn’t a one-time cost. Sure, there’s the down payment, but don’t forget about: Closing costs Property taxes Maintenance & repairs Insurance Monthly mortgage payments If your budget is stretched thin every month or you don’t have an emergency fund, pressing pause might be smart. Owning a home can be more expensive than renting in the short term—and those unexpected costs will show up. 2. You’ve Got a Steady Income and Job Security Lenders like to see consistency. That doesn’t mean you need to be at the same job forever—but a reliable, documented income (ideally for at least 2 years) goes a long way in qualifying for a mortgage. Thinking of switching jobs or going self-employed? That might affect your eligibility, so timing is everything. 3. You Know Your Credit Score—and You’ve Worked On It Your credit score tells lenders how risky (or trustworthy) you are. A higher score opens more doors (literally), while a lower score may mean higher rates—or a declined application. Pro tip: Pull your credit report before applying. Fix errors, pay down balances, and avoid taking on new debt if you’re planning to buy soon. 4. You’re Ready to Stay Put (At Least for a Bit) Buying a home isn’t just a financial decision—it’s a lifestyle one. If you’re still figuring out your long-term plans, buying might not make sense just yet. Generally, staying in your home for at least 3–5 years helps balance the upfront costs and gives your investment time to grow. If you’re more of a “see where life takes me” person right now, that’s totally fine—renting can offer the flexibility you need. 5. You’re Not Just Buying Because Everyone Else Is This one’s big. You’re not behind. You’re not failing. And buying a home just because it seems like the “adult” thing to do is a fast way to end up with buyer’s remorse. Are you buying because it fits your goals? Because you’re ready to settle, invest in your future, and take care of a space that’s all yours? If the answer is yes—you’re in the right headspace. So… Are You Ready? If you’re nodding along to most of these, amazing! You might be more ready than you think. If you’re realizing there are a few things to get in order, that’s okay too. It’s way better to prepare well than to rush into something you're not ready for. Wherever you’re at, I’d love to help you take the next step—whether that’s getting pre-approved, making a plan, or just asking questions without pressure. Let’s make sure your homebuying journey starts strong. Connect anytime—I’m here when you’re ready.
By Martin Jensen September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.